S&P500 Daily Action Areas & Price Targets 19/10/26
S&P500 Daily Action Areas & Price Targets 19/10/26
MONTHLY OPEX
***QUOTING ES1!(Z CONTRACT LEVLES) FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
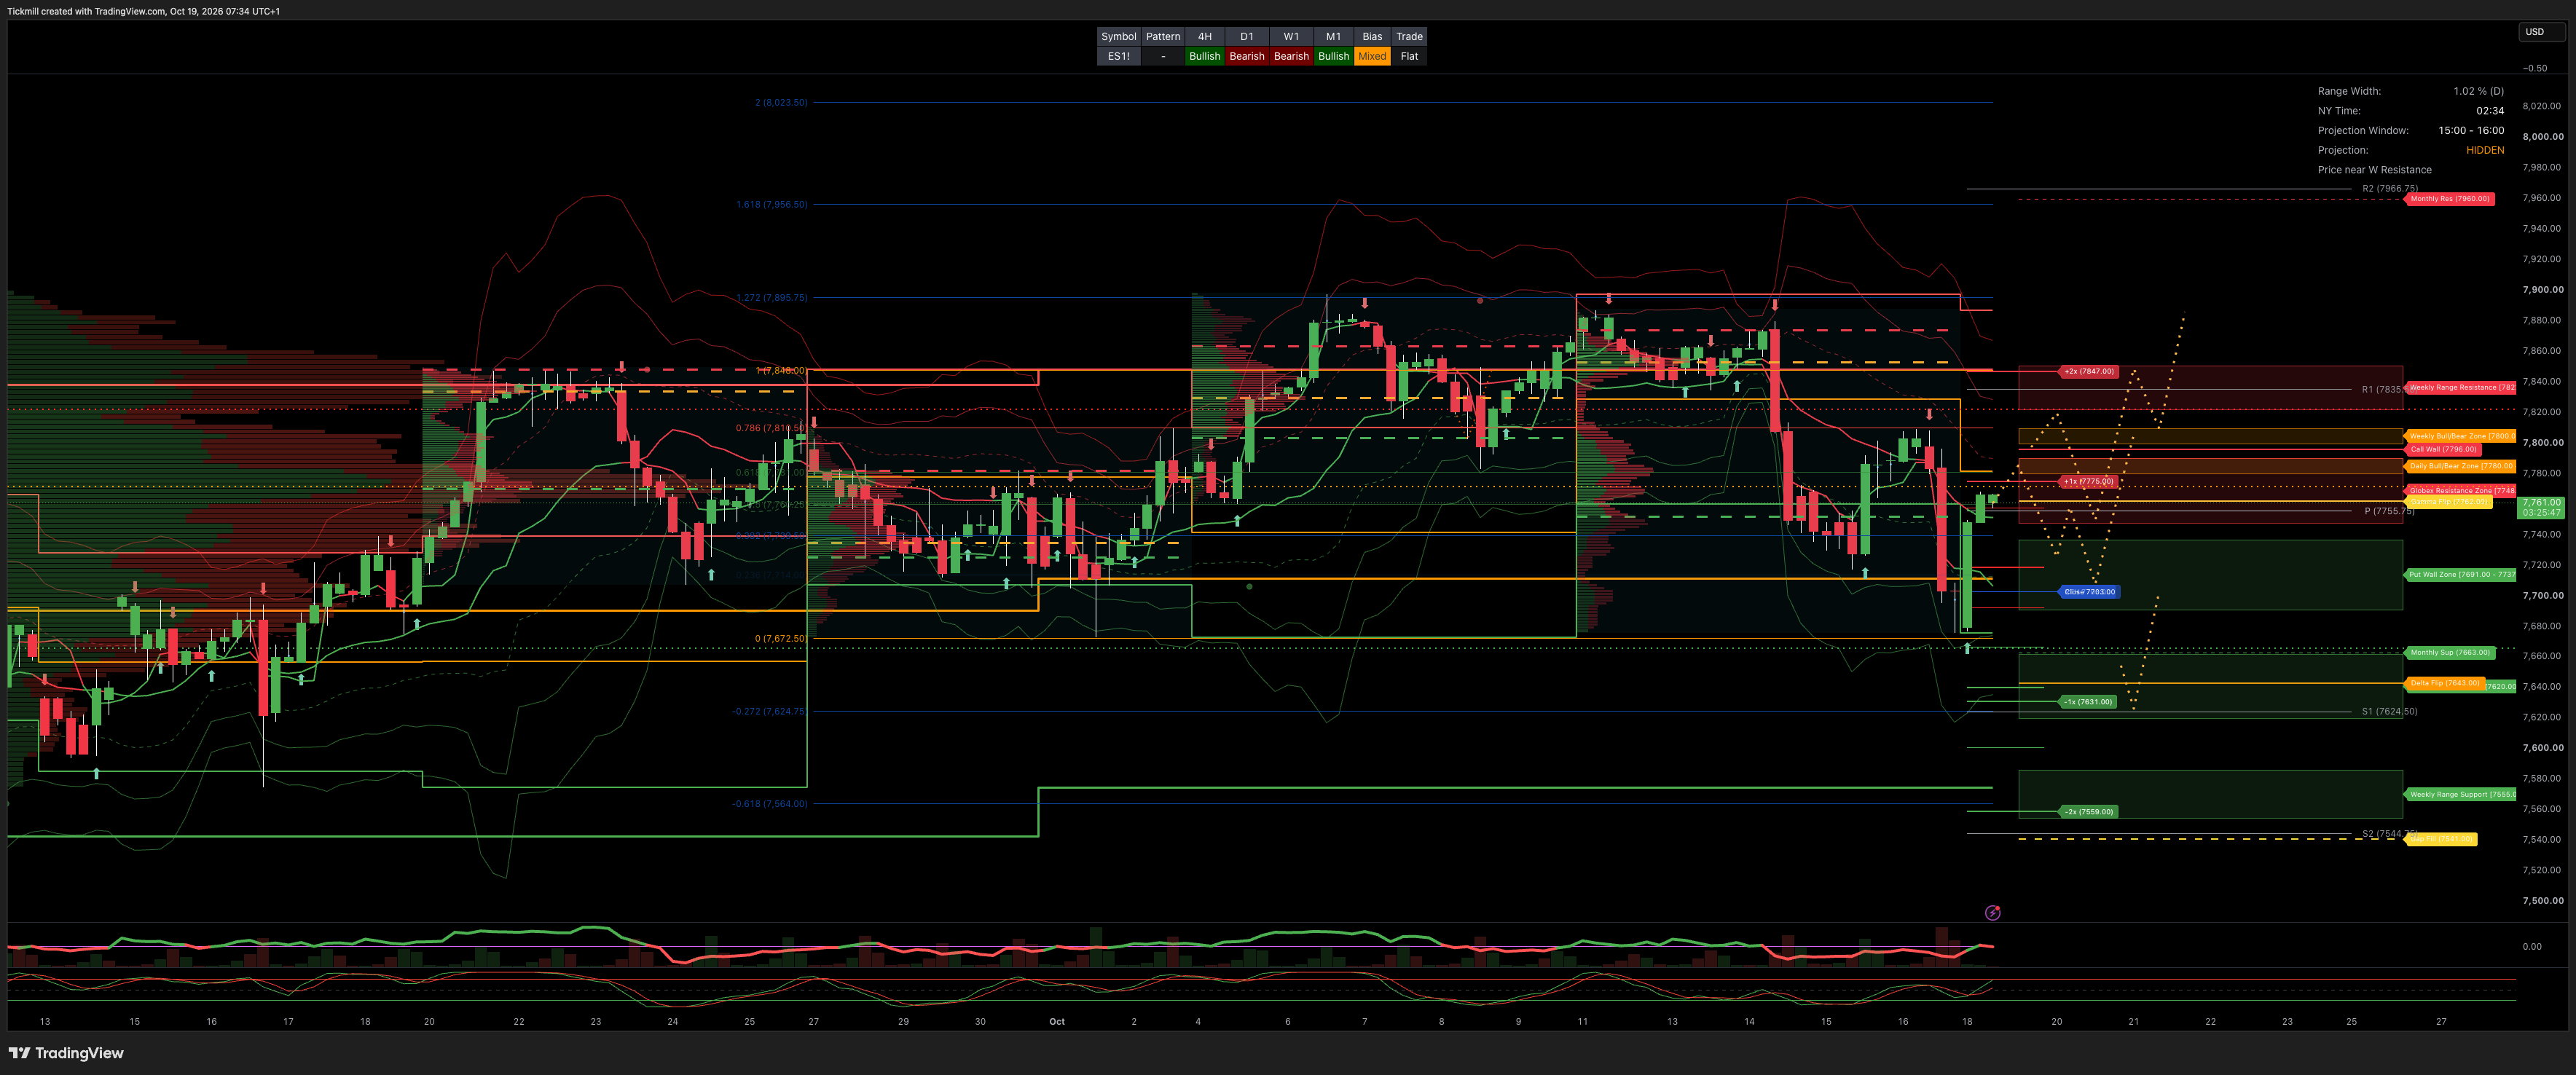
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7960 SUP 7663
WEEKLY BULL BEAR ZONE 7800/10
WEEKLY RANGE RES 7851/22 SUP 7555/86
DAILY BULL BEAR ZONE 7780/90
GLOBEX RANGE SUP 7662/20 RES 7748/90
GAMMA FLIP 7762
DELTA FLIP 7643
CALL WALLS 7796
PUT WALLS 7691/7737
DAILY STRUCTURE - OTFL - 7803
WEEKLY STRUCTURE - BALANCE - 7897/7575
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.7
VVIX-to-VIX A VVIX to VIX ratio of 5.50 (VIX at 19.99, VVIX at 109.91) reflects the market's normal range (5.0-6.0), indicating equity market fear (VIX) and its uncertainty (VVIX) are in sync, with neither acting as a contrarian indicator.
PRIMARY TRADES & TARGETS
SHORT ON REJECT/RECLAIM OF THE DBBZ/WBBZ TARGET HALF GAP - RTH CLOSE
LONG ON ACCEPTANCE ABOVE WBBZ TRAGTE WEKLY RANGE RES ATH’S
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.45 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Upside cap (~7,920–7,950): Dealer gamma hedging at this call strike creates resistance, with market makers likely selling futures into strength and limiting volatility. Downside cushion (~7,270): If SPX drops 5% into Q4, long put gamma may force dealers to buy futures as the index falls, helping stabilize prices. Expiration: December 31, 2026. Strong pinning effects are likely near key strikes into year-end expiration.
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
GOLDMAN SACHS FICC & EQUITY TRADING DESK VIEWS
THE TAKE: A COMPLICATED PHASE IN THE AI SEQUENCE & THE "BOND MARKET SPEED LIMIT"
US equities took a direct hit this week as the AI thematic narrative transitioned into a far more complex phase, forcing an aggressive, broad-based institutional de-risking. The central catalyst was a sudden market-wide shift in focus toward the availability and cost of capital required to sustain the AI investment cycle.
The credit market acted as the primary warning indicator: Goldman Sachs' AI Credit Spreads Basket (GSUCHS30) gapped out to the widest levels of the year. Equity markets followed suit, with the AI Leaders vs. Laggards Basket surrendering the entirety of its ~100% YTD gains accumulated through June—marking the worst single-week performance for the AI leaders cohort since "Liberation Day" in April 2025. Compounding these concerns, a backup in interest rates and elevated deferred Brent crude prices enforced a sharp "speed limit" across high-velocity growth stocks, high-yield credit, and rate-sensitive cyclicals.
CROSS-ASSET FACTOR & FACTOR PAIR DISPERSIBILITY
Quality Factor Surge (
GSP1QUAL): High Quality vs. Low Quality factor pairs surged higher, reflecting a widening tiering gap between fortress balance sheets and cash-burn models.Hedge Fund VIP Drawdown (
GSTHVIPP): The GS Hedge Fund VIP Pair Trade experienced its single worst weekly performance since the March 2020 COVID shock, illustrating the severity of crowded position liquidations.Cyclical Breakdown: Rate and energy pressures pushed the Russell 2000 (
RUT) and Banks (BKX) below their 200-day moving averages, alongside sharp single-stock technical breakdowns in industrial leaders like Caterpillar (CAT), Vertiv (VRT), and GE Vernova (GEV).
DESK FLOWS, OPTION ANXIETY & RECORD TECH LIQUIDATION
Decade-High Tech Liquidation: Franchise flows were heavily skewed toward risk-off across both Long-Only (LO) accounts and Hedge Funds (HFs). The tech sector registered its single largest week of net selling in over 10 years, with supply heavily concentrated in Semiconductors.
Largest Post-ChatGPT AI Net Unwind: Global AI stock exposure experienced its largest patch of net selling since the launch of ChatGPT, bringing institutional exposure down to the 35th percentile of the past year.
Volatility & Options Panic:
CBOE VIX Index: Popped +5.0 full points on the week to close at 20.00.
Term Structure Inversion: The front end of the VIX futures curve inverted into backwardation.
Option Volume Extremes: Heavy buying in VIX upside call options was matched by record notional trading volume in S&P 500 downside puts.
TACTICAL OUTLOOK & UPCOMING CATALYSTS
October Seasonality & Mutual Fund Tax Year-End: Additional supply overhangs are expected through late October driven by active mutual fund tax-loss harvesting ($2.3T AUM ending fiscal year Oct 31) and pre-midterm de-risking.
November Buyback Liquidity Engine: Once pre-earnings blackout windows expire post-reporting, corporate repurchases will take over as the dominant technical driver (November ranks as the 2nd largest buyback month of the calendar year).
Earnings Season Pressure Test: Q3 fundamental earnings strength serves as the "north star" to restore market confidence. Meta Platforms (
META) on Wednesday represents the first critical megacap tech pressure test.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!